



The Australian wealth landscape has completely fractured. Specifically, the May 2026 Federal Budget introduced the most aggressive tax shake-up in a generation. The government has officially targeted negative gearing and traditional capital gains discounts.
Consequently, millions of everyday investors are panicking. Their standard wealth strategies are now mathematically flawed. However, you do not have to be a victim of these legislative changes.
At The SMSF Property Guy, we have engineered the exact solution to this crisis. Specifically, we help elite professionals pivot their capital into a legally protected tax sanctuary. In this guide, we reveal how our team executes SMSF property investing to bulletproof your retirement against the new budget.
The 2026 Federal Budget Bloodbath
First, we must understand the sheer scale of the threat. The government is ruthlessly attacking investments held outside of superannuation. Therefore, holding real estate in your personal name is no longer viable.
For instance, the proposed rules abolish the 50% capital gains tax discount for individuals. Instead, a minimum 30% tax will apply to net capital gains from 1 July 2027. Consequently, your future tax bills will skyrocket.
Furthermore, the budget severely restricts negative gearing. Specifically, you can no longer deduct property losses against your salary for established homes bought after May 12, 2026. Therefore, traditional property investing is fundamentally broken for high-income earners.
The Protected Superannuation Sanctuary
Fortunately, the government left one massive loophole wide open. The budget papers explicitly state these changes do not affect superannuation arrangements. Therefore, your super fund is now the ultimate wealth sanctuary.
By targeting retail investors, the government accidentally supercharged the Self-Managed Super Fund (SMSF). Consequently, shifting your capital into an SMSF is the most logical financial pivot available. Inside this structure, your capital gains tax is effectively capped at just 10%. Furthermore, negative gearing rules remain completely intact for super funds. Ultimately, SMSF property investing is the only way to retain your wealth-building advantages.
How The SMSF Property Guy Protects You
You cannot navigate this massive legislative shift alone. Specifically, attempting a DIY super fund setup on the weekends is financial suicide. Therefore, you need an elite execution partner to guide you.
This is exactly how The SMSF Property Guy protects your capital. We do not just give you generic advice. Instead, we act as the central Property Architect for your entire acquisition.
We transition you from a passive passenger into the active CEO of your wealth. Furthermore, we deploy our proven framework to safely extract your dormant funds. Here is exactly how our team executes your escape plan.
Phase 1: The Advice-Led SMSF Property Pathway
The right defense against the ATO begins with bulletproof legal strategy. Therefore, our process starts with the “Advice-Led SMSF Property Model.” We do not operate as rogue generalists.
I am an SMSF Property Strategist, not a financial planner. Consequently, we partner directly with independent, AFSL-licensed financial advisors and specialist mortgage brokers. They mathematically map your exact trajectory.
Before you ever look at a property, they establish your Corporate Trustee and Bare Trust perfectly. Furthermore, they secure your Limited Recourse Borrowing Arrangement (LRBA) pre-approval. As a result, your financial foundation is 100% legally compliant before we enter the market.
Phase 2: Boots on the Ground Execution
Once your legal mandate is set, The SMSF Property Guy takes over the physical execution. Standard buyers agents sit in air-conditioned offices and buy properties sight-unseen. However, we refuse to operate this way.
We act as your dedicated boots on the ground. Therefore, we physically fly interstate to inspect every single asset. You keep focusing on your high-income career while we do the heavy lifting.
Under the strict rules of an LRBA, you cannot use borrowed money to structurally improve an asset. Consequently, if you buy a dud property with hidden damage, you must drain your cash reserves to fix it. This triggers severe ATO compliance penalties.
My 12-Year Insurance Superpower
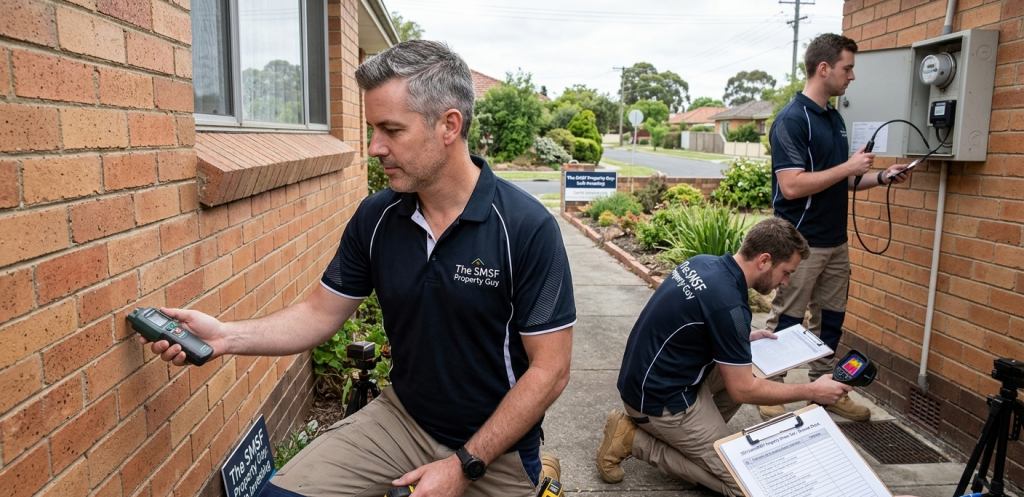
This is where my unique background becomes your ultimate legal shield. Before founding this firm, I spent 12 years as an Insurance Property Assessor. I spent over a decade investigating collapsed roofs, hidden water damage, and foundational cracks.
Therefore, I know exactly where hidden property damage lurks behind fresh paint. I bring the ruthless eye of an insurance assessor directly to your property acquisition.
We deploy our proprietary 155-Point SMSF Property Stress Test on every single asset. Specifically, we hunt aggressively for unapproved renovations, illegal wiring, and environmental threats. Consequently, we spot the exact structural flaws that generalist agents completely miss.
We Reject 99% of Properties
Because our primary goal is protecting your fund from the Australian Taxation Office (ATO), we are ruthlessly selective. Therefore, we reject 99% of the real estate we inspect.
We only target institutional A-grade properties in high-growth national corridors. Furthermore, we ensure the asset is perfectly designed for low-maintenance, high-yield commercial tenancy.
If a property does not pass every single physical check, we walk away immediately. Ultimately, our rigorous inspections save you from catastrophic $80,000 repair bills and massive compliance audits.
Phase 3: The 0% Tax Finish Line
The final step of our execution framework focuses entirely on your retirement finish line. Every day your money sits in a retail fund, you suffer the “Late Start Penalty.” However, our architecture buys back your time.
By leveraging your $250k+ dormant super, you safely acquire a $700k+ physical asset. Therefore, your tenant and your massive employer contributions aggressively smash down the debt for you.
When you hit your Age 60 Preservation Age, you convert your fund into the Pension Phase. Consequently, you unlock 0% tax on rental income and 0% Capital Gains Tax. Ultimately, this completely neutralizes the government’s 2026 budget attacks.
It Is Time to Stop Guessing
The 2026 Federal Budget has officially drawn a line in the sand. You can choose to remain a passive passenger and suffer massive tax hikes. Alternatively, you can step up as the CEO of your Retirement.
If you have a minimum combined superannuation balance of $250,000, you have options. However, transitional budget rules mean you must act quickly to lock in this superior strategy.
Therefore, it is time to stop guessing and start executing safely. You have built the capital, and now you need the elite execution team.
Click here to take our 60-Second SMSF Property Pathway Assessment today. This quick evaluation will instantly validate your capital baseline and tell you exactly how The SMSF Property Guy can safely extract your funds.
Don’t let your hard-earned wealth become a victim of legislative changes. Here are the top three takeaway questions to reflect on right now to see if your current investment strategy is truly protected: