



2026 ATO Update: The Australian Taxation Office is currently cracking down on self managed super fund property valuations and non-lodgements. Here is why DIY compliance is a catastrophic risk to your retirement savings.
The structural reality of navigating a self managed super fund (SMSF) is shifting rapidly. The tax office is no longer letting minor reporting gaps or inaccurate asset valuations slip by. For high-income earners treating their SMSF property strategy like a casual, Sunday night DIY project, the current enforcement climate must serve as an immediate wake-up call. If you want to see exactly how these shifting dynamics impact your investment timeline, you can watch our full masterclass analysis in Episode 5 on YouTube Now
To buy property with super shares zero operational similarities with purchasing a home in your personal name. If you buy a lemon asset personally, your private bank account takes a hit. If you buy a residential property inside super with skewed valuations or hidden compliance cracks, you run the immediate risk of triggering a catastrophic 45% non-compliance penalty from the Australian Taxation Office (ATO). That is a severe enforcement event that can instantly wipe out nearly half of your hard-earned retirement balance overnight.
Furthermore, you cannot rely on traditional banking channels to fix structural errors at the last minute. Ever since the Big Four major banks pulled out of residential SMSF lending, securing finance requires navigating complex limited recourse borrowing arrangements (LRBA) through a highly restricted pool of specialist lenders. Your fund’s compliance must be completely flawless from day one to even pass commercial lending gates.
To find out if your current superannuation balance is exposed to these structural risks or positioned for a high-performance acquisition, take our quick 60-Second SMSF Property Readiness Assessment.
The Dual-Career Edge: From the Docks to Physical Asset Insulation
Before I built my framework as an SMSF property specialist, I spent six years down on the Melbourne wharf as a Deck Foreman. It is a world of steel, concrete, grinding rostered shifts, and non-stop noise. The sparkies, fitters, riggers, and stevedores I worked alongside traded their physical health for a weekly paycheque because they believed a simple deal: break your body now, and your superannuation takes care of you at 65.
But as I watched their hard-earned capital sit languidly inside generic, pooled industry super funds, earning whatever arbitrary, single-digit return the retail fund decided to hand out after heavy management fees, I realised they were passive passengers on their own financial journey. They were the CEO of absolutely nothing.
Compounding that timeline, I also spent 12 years working as an insurance claims manager and licensed property assessor. My entire job consisted of walking into residential assets after structural disasters to tear apart illusions. I had to figure out exactly what was occurring behind the fresh coats of paint, under the floorboards, and inside the foundations.
I have seen pristine, beautifully staged properties that looked immaculate to an uneducated buyer. Yet, directly behind that fresh paint sat completely cracked stumps, severe subfloor rot, painted-over termite damage, and unmitigated structural movement. That dual-career background gave me thousands of hours of physical scar tissue. I learned exactly how a toxic, fundamentally broken property is dressed up to look like a premium asset.
Our Two-Layer Capital Protection Framework
When you marry those two past careers together, you instantly understand why the standard “volume-based” real estate model is broken, and why my firm actively operates on a strict 99% Rejection Rate Guarantee. True capital protection real estate requires a strict, two-layer defense shield before your capital is ever deployed:
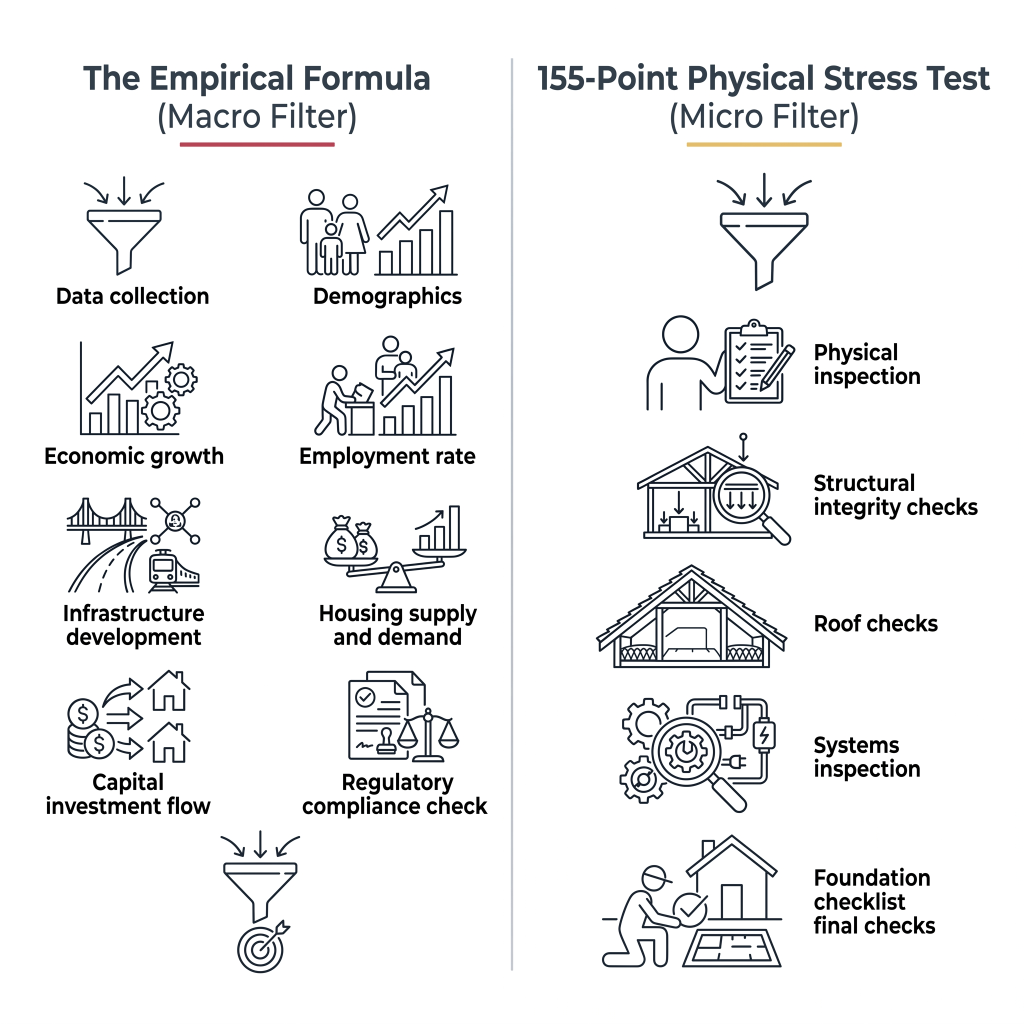
Layer 1: The Empirical Formula (The Macro Filter)
Before we look at a single piece of real estate, the local market must pass nine strict data gates backed by raw empirical evidence. We track diverse economic drivers, micro market size thresholds (minimum 50 house sales annually), localised population metrics, infrastructure pipelines, and hyper-low vacancy constraints. If a suburb fails a single criterion, we eliminate that entire region from our map.
Layer 2: The 155-Point Physical Stress Test (The Micro Filter)
If a market successfully clears the data filter, I do not send a local real estate agent with a vested interest to do a quick video walkthrough. As a dedicated property strategist, I personally book an interstate flight, get on a plane, and walk the asset myself. I run through 155 separate physical checkpoints—inspecting the site contour, looking for council flood overlays, climbing into the roof cavity, and examining the subfloor drainage systems.
If a single checkpoint raises a red flag, we do not try to negotiate a discount. We walk away.
Rejecting 99% of properties is the highest form of asset insulation we can provide to high-income earners who work 60-plus hour weeks. It ensures your capital lands safely in the top 1% of structurally bulletproof, SMSF-grade Australian real estate that stands up to the strictest regulatory scrutiny.
Stop being a passive passenger to a lazy retail super fund while inflation devalues your balance. Step into the CEO seat of your retirement.
If you are ready to skip the generic retail traps and discover exactly how your current superannuation balance stacks up against the strictest regulatory scrutiny, your next step is to evaluate your fund’s true baseline.
Before deploying capital or reviewing assets, you must establish a compliant, data-driven starting point. Click below to run your numbers through our diagnostic framework:
👉 Take the 60-Second SMSF Property Pathway Assessment Find out exactly what your current super balance can purchase inside a secure, compliant structure.