



Cost-of-living pressures are terrifying Australians approaching retirement. For example, recent industry research reveals that 57% of pre-retirees worry about rising costs impacting their lifestyle. Furthermore, 46% of people are completely apprehensive about running out of money once they stop working.
Therefore, relying on a traditional super fund is no longer enough for many. As a result, hard-working professionals are facing severe financial anxiety. However, you do not have to accept this fate.Specifically, there is a proven way to take control of your wealth. That is to say, SMSF property investing offers a powerful solution to beat inflation and secure your future. In this guide, we will show you exactly how to execute this strategy safely.
The True Cost of Retirement Today
Retirement should be your golden era. However, inflation is rapidly eroding the purchasing power of your savings. Additionally, everyday expenses like groceries, petrol, and holidays are skyrocketing.
Consequently, retirees are finding it surprisingly difficult to switch from saving to spending. For example, the latest data shows people believe they need $70,398 annually to retire comfortably.
In contrast, the Association of Superannuation Funds of Australia (ASFA) recommends only $54,840 for a comfortable lifestyle. Therefore, a massive gap exists between expectations and reality.
As a result, a $1 million lump sum today may lose half its purchasing power in twenty years. Most importantly, you need a strategy that generates real, inflation-proof wealth.
Why Retail Super Funds Fall Short
Millions of Australians leave their money in pooled retail super funds. However, this hands-off approach often leads to poor outcomes. Furthermore, you have zero control over where your money is invested.
Additionally, volatile share markets can wipe out years of growth in days. Therefore, you are essentially a passenger on your own financial journey.
In addition, corporate fund fees quietly eat away at your hard-earned balance. Consequently, many high-income earners are looking for an alternative. That is to say, they want tangible assets they can see and touch.
What is SMSF Property Investing?
Taking control starts with establishing a self-managed super fund. Specifically, an SMSF allows you to pool your retirement savings. Furthermore, you act as the trustee, making all the investment decisions.
Therefore, you can use your fund to purchase direct residential or commercial real estate. As a result, SMSF property investing allows you to acquire high-value, tangible assets.
Additionally, this strategy lets you leverage your existing capital. For example, you do not need to pay for the entire property in cash. However, strict regulations govern this process.
The Power of the SMSF Loan
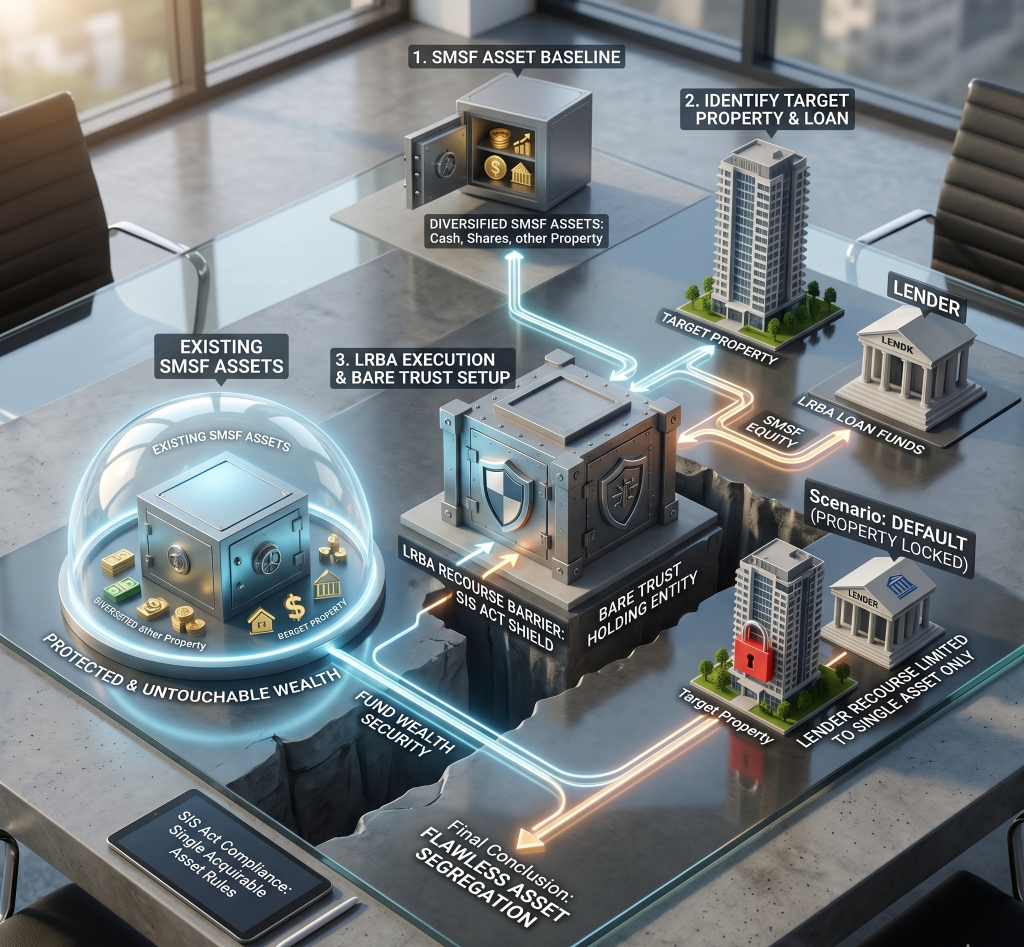
You might wonder how a super fund buys real estate. Fortunately, you can borrow money inside your fund using an SMSF loan. Specifically, this involves a structure called a limited recourse borrowing arrangement (LRBA).
Therefore, your fund uses its cash for the deposit and borrows the rest. Additionally, the “limited recourse” aspect protects your other retirement assets.
For example, if the property loan defaults, the lender cannot touch your cash or shares. Consequently, this provides a massive layer of security for trustees.
However, SMSF borrowing rules are incredibly strict. Therefore, you must work with specialised mortgage brokers to secure finance.
5 Steps to Start SMSF Property Investing
Executing this strategy requires professional guidance and careful planning. Therefore, you should never rush the process. Here are the five critical steps to get started safely.
Step 1: Check Your Super Balance
First, you need sufficient capital to make this worthwhile. Generally, experts recommend a minimum combined balance of $250,000. Additionally, you can pool your balance with up to five other members.
Therefore, a couple can easily combine their accounts to reach this threshold. As a result, you unlock the ability to buy higher-quality real estate.
Step 2: Set Up Your Self-Managed Super Fund
Next, you must legally establish your new super fund. However, this is not a DIY weekend project. Furthermore, you need a compliant Trust Deed and a Corporate Trustee.
Additionally, you must register the fund with the ATO. Consequently, working with a licensed financial advisor is absolutely essential. They will ensure your setup is bulletproof from day one.
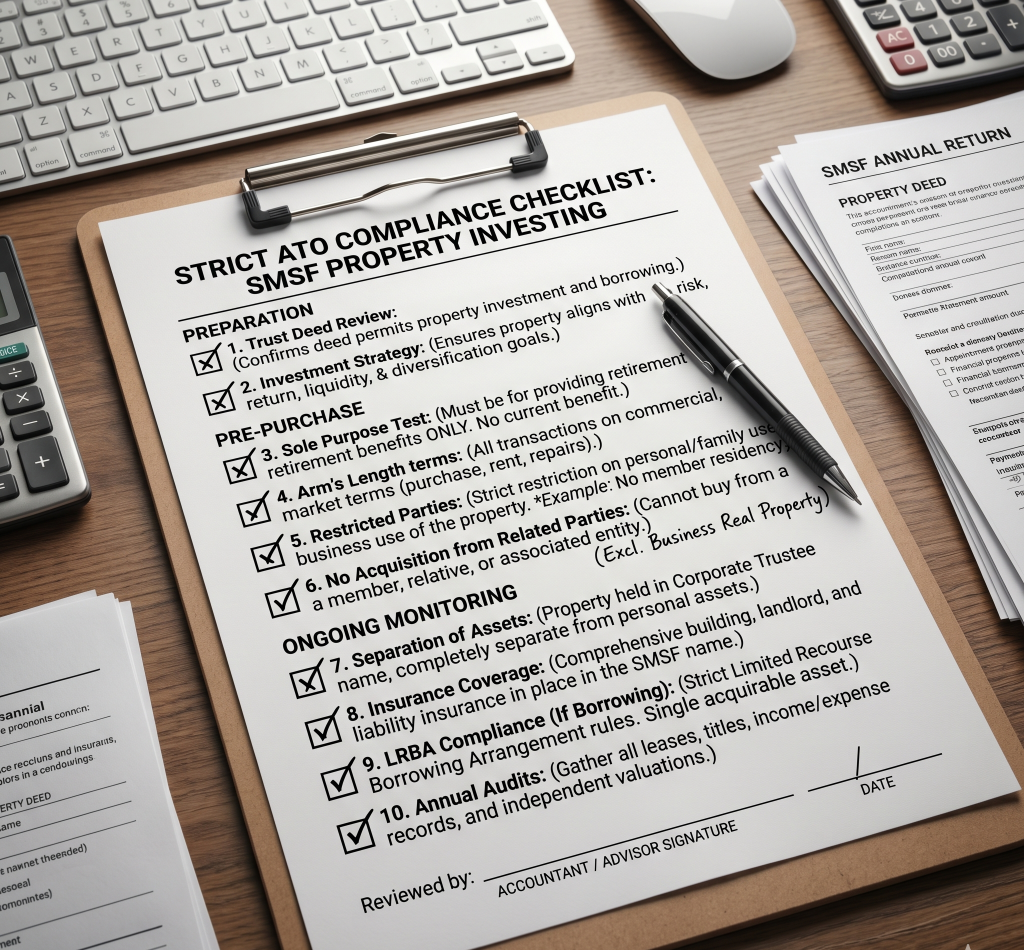
Step 3: Understand SMSF Compliance
Compliance is the most critical aspect of this journey. For example, the ATO monitors self-managed funds ruthlessly. Therefore, you must understand the rules before you look at properties.
Specifically, every asset must pass the “Sole Purpose Test”. That is to say, the investment property must solely provide retirement benefits for members. You cannot live in it or rent it to family members.
Step 4: Secure Your SMSF Loan pre-approval
Before house hunting, you must know your exact budget. Therefore, you need to secure pre-approval for your SMSF loan. However, standard residential bank branches cannot help you here.
Additionally, institutional lenders have strict liquidity requirements. For example, they demand a post-settlement cash buffer of at least 10%. Consequently, you need an expert lending partner to structure this correctly.
Step 5: Buy the Right Investment Property
Finally, you can enter the property market. However, you must buy an institutional A-grade asset. Furthermore, the property must be ready to rent immediately.
For example, buying a “fixer-upper” is a massive compliance trap. That is to say, you cannot use borrowed money to structurally improve the asset. Therefore, you must rely on rigorous data to select the right location.
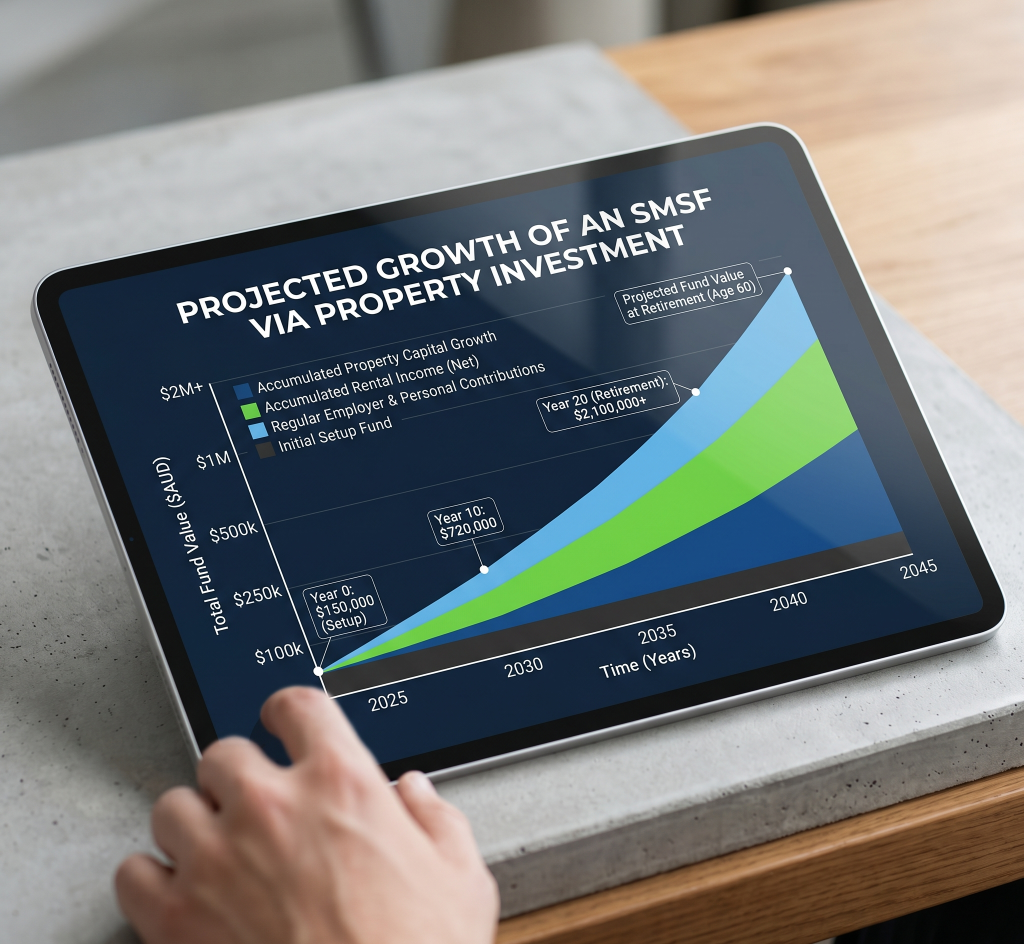
Why Leverage Beats Inflation
Inflation destroys cash sitting in standard bank accounts. However, leveraged property acts as a phenomenal hedge against rising costs. Therefore, SMSF property investing is highly effective.
For example, imagine your fund has $250,000 in cash. Additionally, inflation is running at 4% annually. Consequently, your real purchasing power is dropping rapidly.
In contrast, you use that cash as a deposit on a $600,000 property. Therefore, your capital is now controlling a much larger asset. Furthermore, as the property value grows, your equity multiplies.
Most importantly, the rental income helps pay down the SMSF loan. As a result, your tenant and your employer contributions are building your wealth.
The Incredible Tax Benefits
One of the biggest advantages is the generous tax environment. Specifically, super funds operate under highly favourable tax rates. Therefore, investing inside this structure accelerates your wealth creation.
For example, rental income inside the fund is taxed at just 15%. Additionally, capital gains on properties held for over 12 months are taxed at only 10%.
Furthermore, the benefits explode when you reach retirement. That is to say, when you convert your fund to the “Pension Phase”, the tax rate drops to zero.
Consequently, you pay 0% tax on your rental income. In addition, you pay zero capital gains tax if you sell the property. Ultimately, this is how high-income earners create generational wealth.
Understanding the Risks Involved
Every financial strategy carries some level of risk. Therefore, you must enter this process with your eyes wide open. However, proper planning mitigates almost all of these dangers.
For example, property is an illiquid asset class. That is to say, you cannot sell a bedroom if you suddenly need cash. Consequently, you must maintain strong liquidity buffers in your fund’s bank account.
Additionally, interest rate fluctuations can impact your cash flow. Therefore, you must stress-test your borrowing capacity thoroughly. Furthermore, failing to meet ATO compliance can trigger massive financial penalties.
As a result, you must use a professional execution team. Specifically, attempting to do this yourself is a recipe for disaster.
Fatal Traps to Avoid
Many investors fall into preventable traps. Therefore, you must learn from the mistakes of others. Here are the most common pitfalls we see in the market.
Firstly, people sign property contracts before setting up their Bare Trust. Consequently, they are forced to pay stamp duty twice. This is a devastating financial error.
Secondly, investors buy off-the-plan apartments. However, these properties frequently suffer from terrible valuations at settlement. Additionally, they often fail the strict SMSF borrowing rules of major lenders.
Thirdly, people try to renovate using borrowed funds. Specifically, this directly breaches the ATO “Single Acquirable Asset” legislation. Therefore, you must only buy structurally sound, low-maintenance properties.
Finally, investors use generalist accountants instead of specialists. As a result, their trust deeds are drafted incorrectly. Furthermore, this leads to rejected loan applications and massive delays.
The “Boots on the Ground” Advantage
Sourcing the right investment property takes hundreds of hours. However, busy professionals simply do not have the time. Therefore, they often buy properties sight-unseen off the internet.
Consequently, they end up with compromised assets in poor locations. In contrast, working with a specialist property strategist removes this risk entirely.
For example, our team physically inspects every single property. Additionally, we run every asset through a clinical 155-point stress test. Therefore, we ensure it meets all strict ATO compliance regulations.
Furthermore, we handle the entire negotiation process. As a result, you can focus on your career while we build your portfolio.
How to Overcome Retirement Anxiety
Let us return to the core problem. Rising costs are causing severe retirement angst. However, worrying about the future will not change your reality.
Therefore, you must take decisive, strategic action today. Additionally, you must transition from being a passive passenger to an active CEO.
Specifically, you need a strategy that targets your Preservation Age. For example, we aim to help clients retire comfortably at age 60, not 67. Furthermore, we use the property’s rental yield to aggressively smash down the debt.
Consequently, you cross the finish line with an unencumbered, tax-free asset. Most importantly, this creates the $100,000+ passive income you need to live without stress.
Creating Your Personalised Strategy
No two super funds are exactly alike. Therefore, your strategy must be tailored to your specific financial situation. Additionally, your timeline to retirement dictates your risk profile.
For example, a 40-year-old doctor has 20 years to let compound growth work. In contrast, a 55-year-old executive needs a higher-yielding asset to accelerate their debt pay-down.
Consequently, we always start with a deep-dive strategic review. Furthermore, we collaborate with independent, licensed financial advisors to map your exact trajectory.
Therefore, you receive a mathematically proven blueprint before you spend a single dollar. In addition, this unified approach guarantees your setup is 100% legally compliant.
The Role of Property Managers
Once you secure the property, the work is not over. However, you cannot manage the property yourself. Specifically, ATO rules require all transactions to be strictly arm’s length.
Therefore, you must hire a professional property manager. Additionally, they will ensure the tenant pays fair market rent. Furthermore, they handle all maintenance requests and lease agreements.
Consequently, your rental income flows seamlessly into your super fund bank account. As a result, you maintain perfect compliance for your annual independent audit.
Frequently Asked Questions
Many people have questions before taking the leap. Therefore, we have answered the most common queries below.
Can I live in my SMSF property? No. However, you can buy commercial premises and lease it back to your own business. Therefore, business real property is the only exception to the rule.
How much deposit do I need? Generally, lenders require a 20% to 30% deposit. Additionally, you must cover stamp duty and legal fees from your cash balance. Furthermore, you must retain a 10% liquidity buffer after settlement.Can I build a house with my super? Technically yes, but it is incredibly difficult. For example, you cannot use an LRBA loan to fund construction. Therefore, you must pay for the entire build using your fund’s liquid cash. Consequently, we highly recommend buying established properties instead.
The Time to Act is Now
Every day your money sits in cash, inflation wins. Therefore, delaying your wealth strategy is costing you thousands of dollars. Additionally, the property market continues to move upward while you wait.
Consequently, the longer you hesitate, the harder it becomes to secure an A-grade asset. Furthermore, the government frequently changes superannuation legislation.
As a result, you must capitalise on the current rules while they are highly favourable. That is to say, there is no better time to execute your retirement architecture.
Final Thoughts on Wealth Creation
Ultimately, your retirement lifestyle is entirely in your hands. Therefore, you can choose to accept the default, low-growth retail super pathway. However, you can also choose to engineer a superior outcome.
Additionally, SMSF property investing provides the perfect vehicle for high-income earners. Furthermore, it combines the power of leverage, tax minimisation, and tangible asset growth.
Consequently, it is the ultimate antidote to cost-of-living anxiety. In addition, it allows you to reclaim years of your life and retire on your own terms.
Conclusion
In summary, rising living costs are causing unprecedented retirement anxiety. However, you do not have to settle for financial insecurity. By setting up a self-managed super fund, you gain absolute control over your future. Furthermore, utilising an LRBA to buy real estate is a proven wealth-generation strategy. Therefore, you can outpace inflation and build a tax-free income stream. Are you ready to stop worrying and start executing? Click here to book a FREE Strategy Session with our expert team today. Discover how SMSF property investing can secure your golden years permanently.