



You are a highly successful, busy professional. You have poured decades into your career. Additionally, you are grinding out sixty-hour clinic weeks or demanding FIFO swings. Consequently, you have built a massive superannuation balance.
However, you are tired of being a passenger on your own financial journey. Recent data shows that 46% of pre-retirees are terrified of outliving their savings. Therefore, you decide to take control. You spot an interstate investment property online.
The photos look glossy. Furthermore, the rental yield looks perfect. You think you can set up a Self-Managed Super Fund and buy it yourself. Stop right there. That exact thought process is the first step toward complete financial suicide.Specifically, DIY execution is incredibly dangerous. In this guide, we reveal the correct framework for SMSF property investing. We will show you how to avoid catastrophic ATO penalties and secure your tax-free retirement safely.
The Illusion of the DIY Property Purchase
The internet makes buying real estate look deceptively simple. For example, property portals offer 3D virtual tours and perfectly staged photos. Consequently, high-income earners assume they can manage complex acquisitions from their study.
However, treating a highly regulated financial strategy like booking a holiday is a fatal mistake. Your retirement capital is your most valuable financial asset. Therefore, you cannot afford to cut corners to save a few dollars in execution fees.
Specifically, DIY investors frequently skip critical legal steps. Furthermore, they trust cheap, generalist advisors instead of true specialists. As a result, they unknowingly expose their entire superannuation balance to massive compliance risks.
The Story of Dr. Evans
Let us look at a real-world scenario. We will call him Dr. Evans. He is a brilliant surgeon at the very top of his field. His entire life is a testament to precision and hard work.
He had over $500,000 trapped in a pooled industry super fund. However, watching corporate fund fees slowly eat away at his balance felt like a slow bleed. Therefore, he started researching the SMSF Property Pathway.
He learned he could take control of his wealth. Specifically, he discovered he could set up an SMSF. Additionally, he could use a Limited Recourse Borrowing Arrangement (LRBA) to buy high-value, physical property.
The Incredible Mathematical Advantage
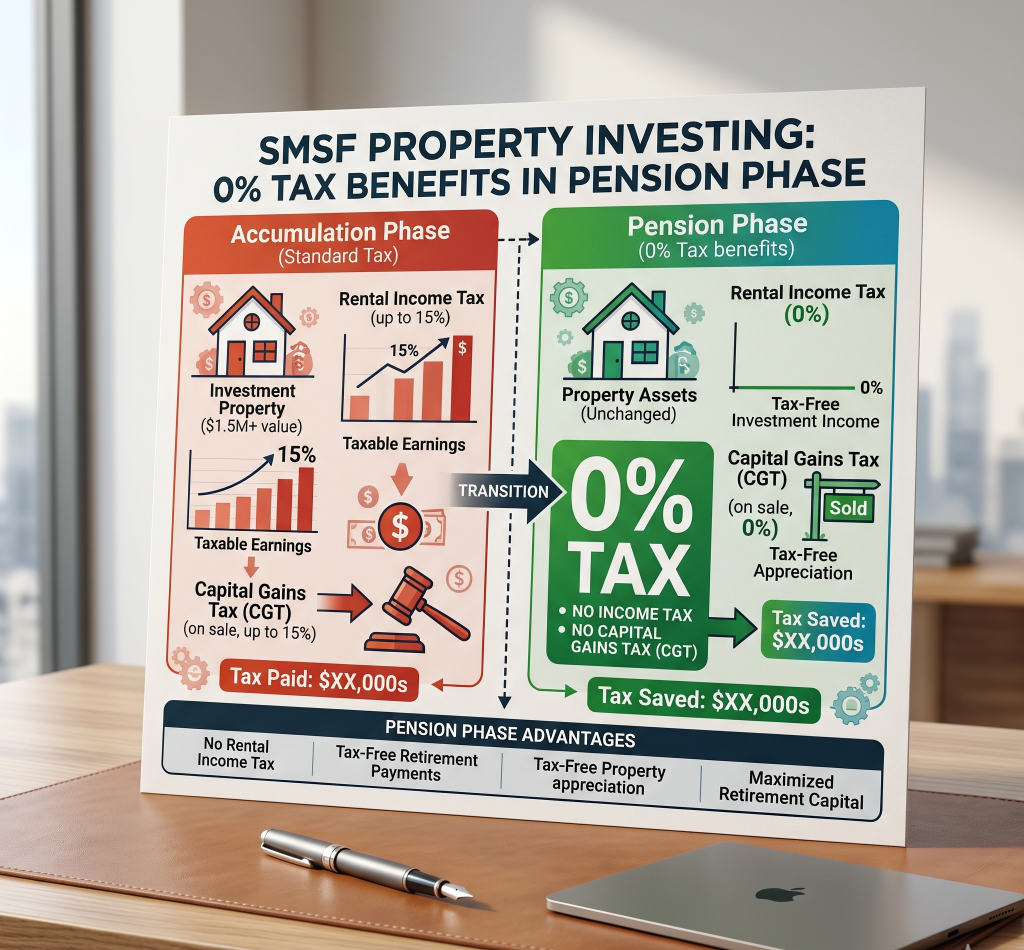
The tax environment for super funds completely blew his mind. For instance, the system only taxes rental income at 15%. Furthermore, capital gains are taxed at just 10% if held for over twelve months.
Most importantly, the tax rate drops to 0% once he hits his Preservation Age at 60. Therefore, the mathematical idea was absolutely bulletproof. He could build massive, tax-free wealth.
However, the problem was the execution. Dr. Evans was completely time-poor. He simply did not have time to fly from Melbourne to Brisbane every weekend to look at real estate.
The Fatal Execution Mistake
Despite his lack of time, the internet made the process look easy. He found a neat-looking, three-bedroom house in Brisbane. The online pictures were absolutely perfect.
He thought to himself, “Why would I pay a specialist strategist when I can sort this out myself?” Consequently, he decided to manage the entire acquisition alone. He wanted to cut out the professional execution fees.
This was his fatal mistake. Ultimately, he was treating a highly regulated financial architecture with a casual, weekend approach. He was about to hit the “Execution Wall” at full speed.
Act 1: The Cheap DIY Legal Setup
Here is the exact script Dr. Evans followed to disaster. See if any of this sounds familiar to your own research. First, he paid a cheap online, generalist accountant to set up his Corporate Trustee.
He quickly ticked the boxes and signed the forms. Poof—he was suddenly a company Director. However, he did not understand the gravity of his new title.
Specifically, he did not realize the sheer weight of the Superannuation Industry Supervision (SIS) Act. He had just placed massive legal responsibility on his own shoulders. Furthermore, his generic accountant provided zero strategic advice regarding borrowing limits.
Act 2: The Sight-Unseen Purchase
Next, he used a standard retail mortgage broker to get an LRBA. Standard brokers rarely understand the complex liquidity requirements of super funds. Nevertheless, with pre-approval in hand, he made an offer on the Brisbane house.
He relied entirely on a cheap $500 building inspector recommended by the selling agent. Unsurprisingly, the report came back “mostly clean.” Therefore, he confidently signed the contract.
However, he did not just buy a house. He bought a collection of curated photographs. He was completely blind to what was actually lurking behind the fresh paint.
Act 3: The Rapid Unraveling
Settlement went through smoothly. For two months, everything seemed perfectly fine. Rent was coming in, and Dr. Evans felt like a financial genius.
Then, a heavy Brisbane storm hit the city. Suddenly, water poured through the master bedroom ceiling. Additionally, the new tenant complained of a damp, mouldy smell that had been there since day one.
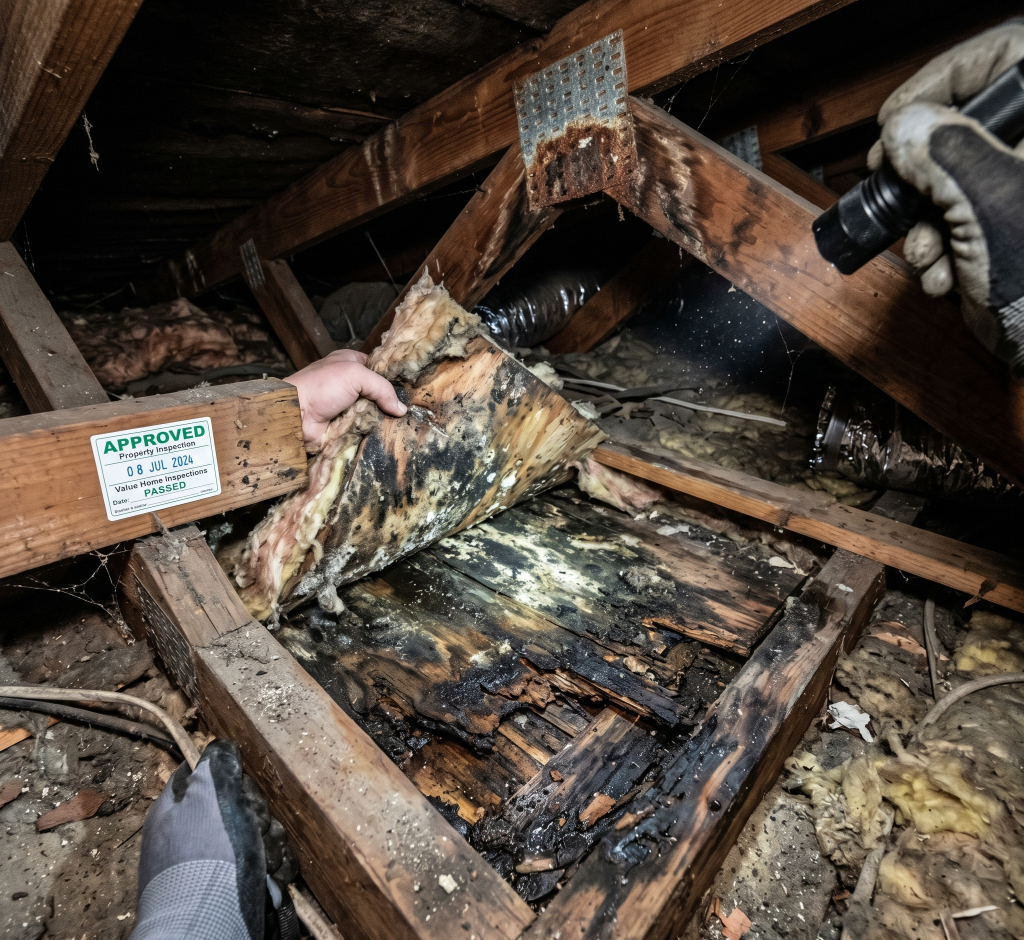
Dr. Evans sent a specialist consultant to investigate. The ugly truth quickly came out. The roof was completely shot. It was just patched up cosmetically for a quick sale.
The Catastrophic Repair Bill
The structural issues were far worse than a leaky roof. The internal timber beams were actively rotting away. Worse still, the bathroom had been illegally renovated without council permits.
Consequently, this lack of waterproofing led to years of severe subfloor water damage. The entire framework of the house was compromised.
The specialist handed Dr. Evans the repair bill to make the property legally safe. The total cost was a staggering $80,000.
Act 4: The ATO Compliance Nightmare
Dr. Evans panicked. He thought, “Okay, I have an investment loan. I will just borrow more money to fix it.” He immediately called his standard mortgage broker.
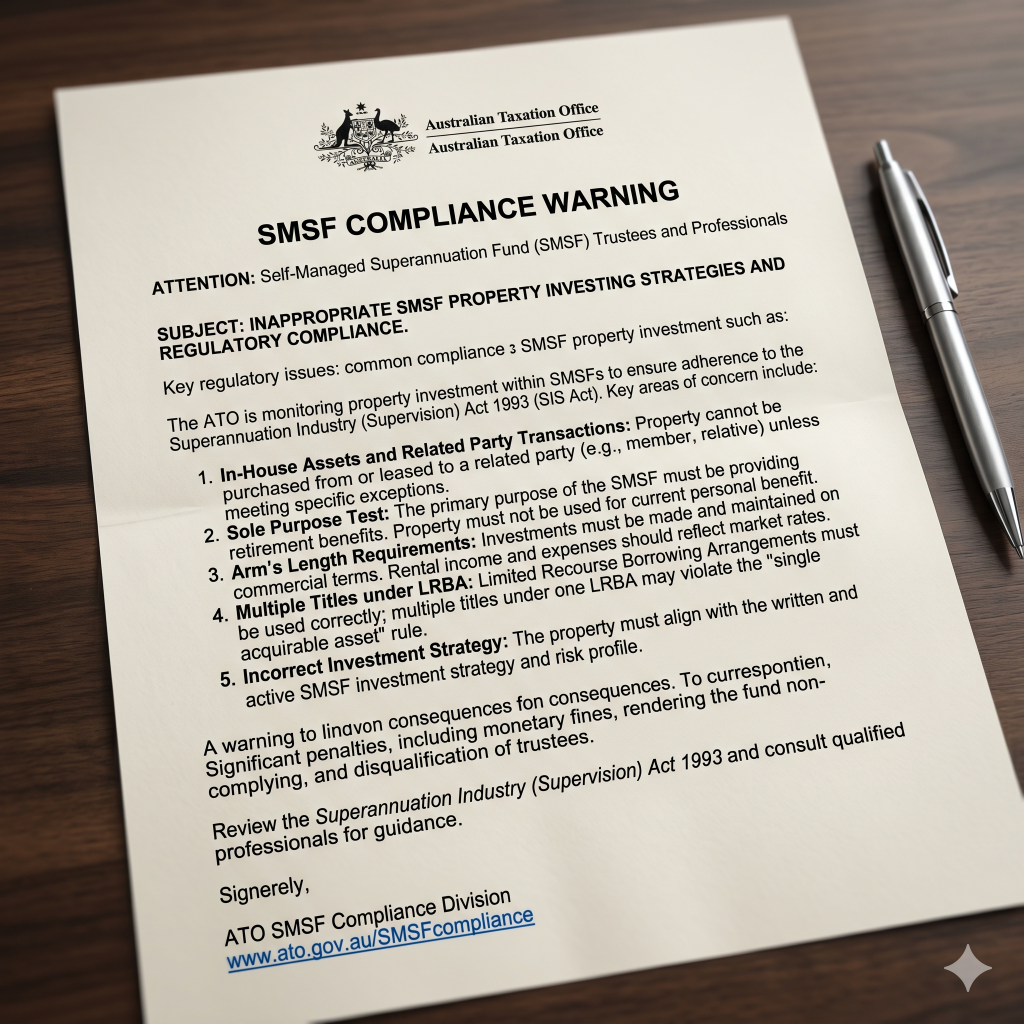
However, his broker delivered devastating news. Under the strict rules of an LRBA, you absolutely cannot use borrowed money to improve a property.Replacing an entire roof structure and fixing an illegal bathroom renovation is classed by the ATO as an improvement, not a simple repair. Therefore, the Australian Taxation Office strictly prohibits using LRBA funds for this work.
The Brink of Financial Ruin
That massive $80,000 bill could not come from the loan. Instead, it had to come directly out of the liquid cash reserves sitting inside his SMSF bank account.
Paying that unexpected bill would completely cannibalize his fund’s mandatory cash buffer. Consequently, he would be unable to pay the annual independent audit or the ATO levies. Furthermore, he would struggle to make loan repayments if the property sat vacant during repairs.
If he used borrowed funds anyway, he would immediately breach the “Single Acquirable Asset” rules. As a result, the ATO could declare his fund non-compliant. This triggers a catastrophic 45% tax penalty on all his assets. He was paralyzed.
The Script for Professional Success
Now, let us rewind and completely flip the script. We must give Dr. Evans a second chance and put him on the professional pathway.
The script for true wealth creation is not about doing it all yourself on weekends. Instead, it is about building a Unified SMSF Execution Team.
You must step up as the CEO of your retirement. Therefore, you delegate the heavy lifting to licensed specialists. Here is exactly how we engineer flawless acquisitions.
Phase 1: The Legal Financial Strategy
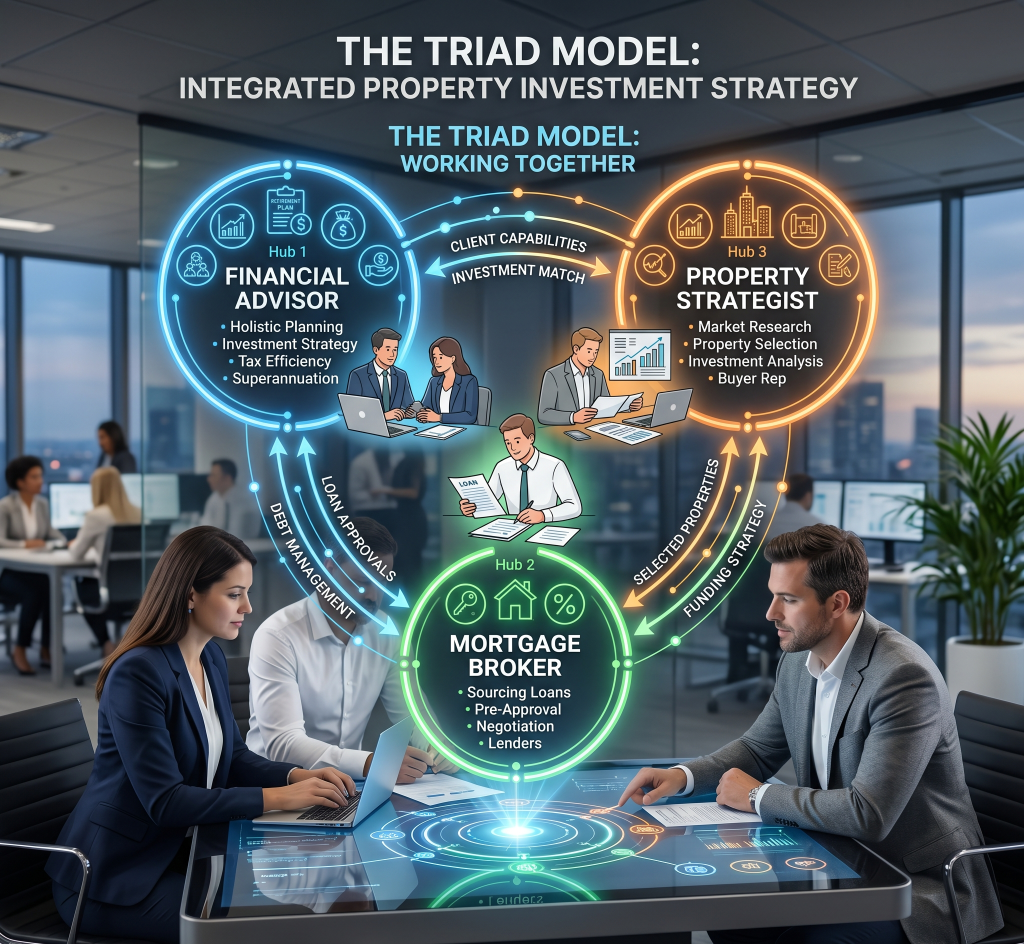
The right script never begins with scrolling real estate websites. It always begins with bulletproof legal strategy. We utilize the “Triad Model” to protect your capital.
I am an SMSF Property Strategist. I am not licensed to give personal financial advice. That is exactly why our professional pathway starts by handing you over to elite, AFSL-licensed financial advisors.
Before you ever look at a physical property, they mathematically map your exact super trajectory. Furthermore, they provide the legally required Statement of Advice (SOA).
Bulletproofing the Architecture
Your financial advisory team establishes your Corporate Trustee perfectly. Additionally, they draft a compliant Bare Trust to hold the physical asset.
Most importantly, they verify your exact capital baseline and borrowing capacity. Consequently, we ensure your financial foundation is legally bulletproof before we ever take a step into the market.
Therefore, you never have to guess your budget. You know exactly what your fund can safely acquire without risking your liquidity buffers.
Phase 2: Boots-on-the-Ground Execution
Armed with the strict legal mandate from your advisory team, we step in. We act purely as your physical execution partner. And here is the massive difference in our service.
We are not standard buyers agents who sit in air-conditioned offices buying sight-unseen. We act as your Boots on the Ground. We fly interstate. We go wherever the data dictates the best growth.
Therefore, we take on the physical burden of the property search. You keep focusing on your high-income career while we do the heavy lifting.
The 12-Year Insurance Superpower
Before I became an SMSF Property Strategist, I spent 12 years in the insurance industry. Specifically, I specialized as a Claims Manager and Property Assessor.
I spent over a decade assessing claims for collapsed roofs, severe water damage, and foundational cracks. I worked for Australia’s biggest insurance companies, inspecting hundreds of damaged homes.
Consequently, I know exactly where hidden property damage lurks behind fresh paint. This deep technical knowledge is our ultimate superpower. It is the exact skill set required to protect superannuation capital.
The 155-Point SMSF Property Stress Test
We deploy our proprietary 155-Point SMSF Property Stress Test on every single asset. We do not rely on local property managers to do this for us.
Structural & ATO Integrity: We go way beyond the cosmetic surface. We hunt aggressively for unapproved renovations and illegal wiring. We look for structural stress that would instantly trigger an ATO compliance breach under your LRBA.
Environmental Threats: We ruthlessly assess council flood zones and building overlays. You simply cannot see these environmental risks on a standard virtual tour.Yield Drivers: We ensure the asset is an institutional A-grade property. It must be perfectly designed for low-maintenance, high-yield commercial tenancy.
Rejecting Compromised Real Estate
This ruthless stress test would have instantly red-flagged Dr. Evans’ Brisbane property. The illegal bathroom renovation and the rotting roof would have been caught on day one.
Consequently, we would have rejected the property before a contract was ever drafted. We walk away from 99% of the properties we inspect.
This is the exact execution you pay for. It is not an unnecessary cost. Rather, it is the ultimate legal shield for your hard-earned retirement capital.
Beating Retirement Angst With Strategy
Dr. Evans’ horror story highlights a deeper anxiety haunting hardworking Australians. We call this phenomenon Retirement Angst.
According to the latest 2026 figures from the Association of Superannuation Funds of Australia (ASFA), living costs are soaring. To live a comfortable retirement, a couple now needs an income of over $77,000 per year. A single person needs over $54,000 annually.
A retail super balance of $500,000 sounds like a lot of money. However, you must realize it has to last you for 30 years. Meanwhile, inflation destroys its purchasing power daily. You simply cannot save your way to true wealth in cash.
The Accelerated Preservation Strategy
This mathematical reality is where the Accelerated Preservation Strategy becomes your ultimate antidote. When executed correctly alongside elite professionals, an SMSF gives you massive advantages.
Institutional Leverage: You use your $250k+ cash baseline to safely control a $600,000+ A-grade property. Therefore, you earn capital growth on the full asset value, not just your deposit.
Inflation Hedging: As inflation rises, your property value and rental yields rise simultaneously. However, your debt is slowly eroded by those cheaper dollars.The 7-Year Reclaim: Your massive employer contributions and tenant yields aggressively smash down your LRBA debt. When you hit your Age 60 Preservation Age, you unlock 0% tax on rental income and 0% Capital Gains Tax.
Frequently Asked Questions
Many professionals have questions before taking control of their super. Therefore, we have answered the most critical queries below.
Why can’t I use borrowed money to renovate? The ATO mandates that properties purchased with an LRBA remain a “Single Acquirable Asset.” Therefore, using borrowed funds to structurally improve a home changes the nature of the asset, triggering severe compliance breaches.
Do I really need a minimum of $250,000? Yes. Establishing the Corporate Trustee, securing financial advice, and retaining a 10% cash buffer requires substantial liquidity. Consequently, attempting this strategy with lower balances places your fund at high financial risk.
Can I manage the investment property myself? No. All transactions must remain strictly arm’s length to satisfy ATO auditors. Therefore, you must employ an independent, licensed property manager to handle the tenancy.
Stop Guessing and Start Executing
You are the CEO of your own retirement. Therefore, you must choose which script you follow today.
You can choose the DIY path of compliance nightmares and financial ruin. Alternatively, you can choose the professional execution team and secure your wealth safely.
If you have a minimum of $250,000 in your super fund, it is time to stop guessing. You must discover if this architecture is mathematically viable for your specific situation. Click here to take our 60-Second SMSF Property Readiness Assessment. It will instantly validate your capital baseline and tell you exactly what your next steps are to safely extract your funds. Stop waiting and start building your legacy today.